
Costco is one of the few big retailers where your choice of card is decided before you reach the register. In the United States, the warehouses take Visa credit cards and almost nothing else on the credit side.
That makes picking a Visa credit card for Costco a real decision, not a formality. The right card can shave a few percent off your gas, restaurant, and warehouse spending. Bad habits can wipe that gain out with interest.
This guide covers why the rule exists, which cards work, how the Costco Anywhere Visa Card by Citi pays, a worked example you can redo with your own numbers, and where the card falls short.
One caution first. This is general information, not financial advice, and card terms change. Confirm the current rates, fees, and membership rules on the issuer’s site before you apply.
Why Costco Only Takes Visa
The rule is not a quirk. It comes from a business deal. According to Mental Floss, card companies typically charge merchants fees of up to 3%, which adds up to large sums for a retailer Costco’s size.
Costco’s arrangement with Visa makes Visa the only credit card accepted at its warehouses and gas pumps. In return, the report says, Visa’s fees for Costco are “virtually zero.”
The deal dates to 2015. Before that, Costco had roughly a 16-year relationship with American Express, which ended when the two could not agree on new terms. Visa and Citigroup took over, with Citi as the co-branded card issuer.
Most of the story is about fees, and the benefit flows to Costco. That is also why the retailer can keep its prices low on many items, though that last point is general reasoning, not a sourced claim.
What You Can Use at the Register
If you do not hold a Visa credit card, you still have options. The same Mental Floss report lists the other ways to pay: almost any debit card, including Mastercard-branded debit, cash, checks and traveler’s checks, electronic benefit transfer (EBT), and mobile payments such as Apple Pay.
Mastercard credit cards are accepted for online orders on Costco’s website but not in warehouses. A Costco-branded Mastercard exists only for shoppers in Canada.
Payment rules can change by country and by year, so check Costco’s current policy for your location before you rely on any of this.
A practical point follows from that list. Any Visa credit card, from any bank, works at the warehouse. You do not need the co-branded card just to pay. The question is whether the co-branded card earns you more than the Visa you already hold.
The Costco Anywhere Visa Card by Citi
The co-branded option is the Costco Anywhere Visa Card by Citi. Two independent sources, creditcards.com (page updated March 9, 2026) and Experian, list the same terms.
| Spending category | Rewards rate |
|---|---|
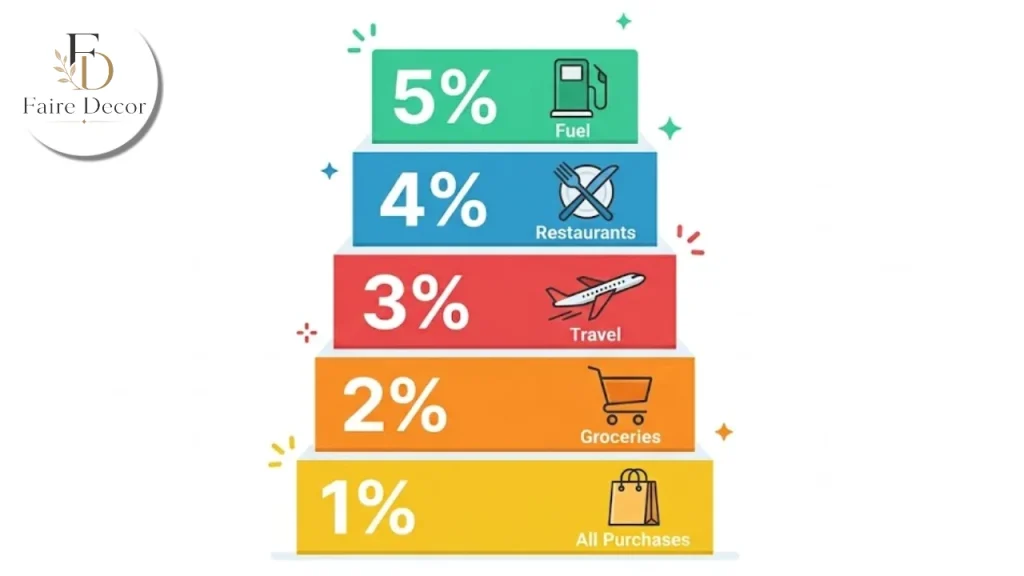
| Gas at Costco | 5% |
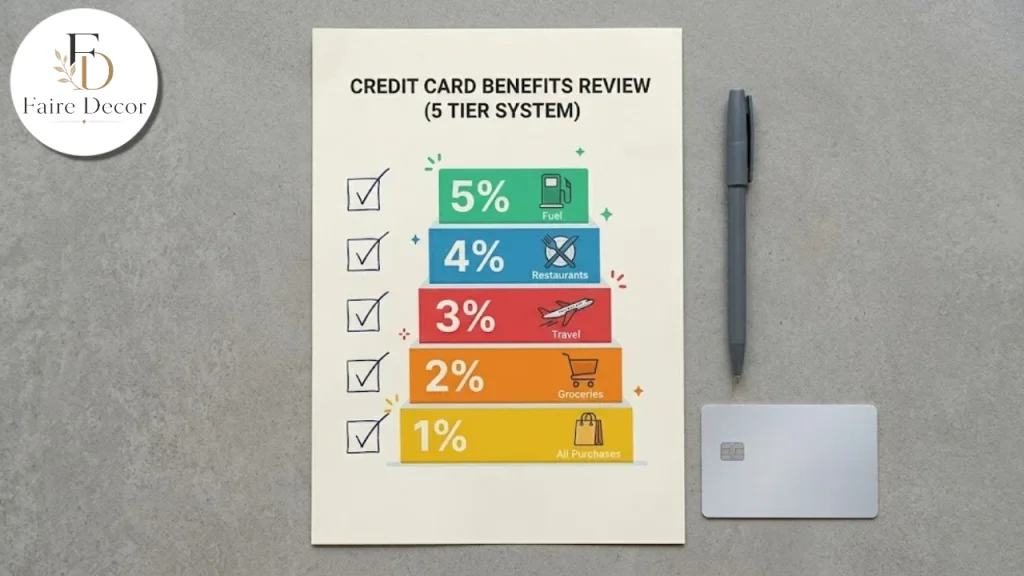
| Other eligible gas and EV charging | 4% on the first $7,000 combined per year, then 1% |
| Restaurants and eligible travel, including Costco Travel | 3% |
| Other purchases from Costco and Costco.com | 2% |
| All other purchases | 1% |
Beyond the rates, both pages report a $0 annual fee for cardholders, with a paid Costco membership required. The ongoing APR is 18.99% to 26.99% variable, with no introductory APR and no foreign transaction fees.
Experian lists the recommended credit as “Exceptional” using the FICO Score 8 model, and creditcards.com labels it for an “Excellent” credit range. In plain terms, this is a card for people with strong credit.
These figures are a snapshot. The card’s own terms live on Citi’s site, which I could not open while preparing this guide, so treat the table as a starting point and verify it.
How the Annual Reward Certificate Works
This is the part many shoppers miss. The card does not pay rewards to your statement each month. It pays an annual credit card reward certificate, redeemable for cash or merchandise at U.S. Costco warehouses, including Puerto Rico.
That has three consequences worth thinking about. These are general observations built on that description, not Citi’s wording.
First, the money arrives once a year, so you wait to see the total. Second, the certificate is tied to Costco, so you can only use it there. Third, you need to remember to redeem it.
For a frequent Costco shopper, those limits cost little. For someone who visits twice a year, a certificate that can only be spent in a warehouse is less flexible than plain cash back that lands in your bank account.
Check the current redemption rules on the issuer’s page, including how and when the certificate is issued and any expiry date. I did not find those details in the sources I could read.
Membership and the Card: How They Fit Together
The card is not a standalone product. Both sources say a paid Costco membership is required, and the $0 annual fee applies to cardholders who hold one. In effect, the real yearly cost of the card is the membership you would pay for anyway.
That framing helps with one question: is the membership worth it? The card cannot answer that for you. Check the current fee for the tier you want, then ask whether your Costco savings plus card rewards beat what you would spend elsewhere.
A simple test is to add up what you buy at Costco in a year, estimate what the same items cost at your usual store, and subtract the membership fee. Add the card rewards afterward. If the total is close to zero, the membership is not doing much for you.
Costco offers more than one membership level. I did not find a sourced description of the tiers, so check Costco’s own membership page for the current options and prices, and note whether a higher tier changes the benefits you get from the card.
Also remember that a visa credit card for Costco rewards the spending you already do. It should lower your costs, not raise your spending. If you buy more because you hold the card, the math flips.
Gas Rewards in Detail
Gas is where this card tends to stand out, so it deserves a closer look. The sources list 5% back on gas at Costco and 4% on other eligible gas and EV charging, with the 4% tier capped at $7,000 of combined spending a year before dropping to 1%.
Take a driver who spends $200 a month at a Costco station. That is $2,400 a year, and at 5% it earns $120. A driver who spends the same $200 a month at other eligible stations earns 4% on it, or $96, as long as the combined total stays under the cap.
The creditcards.com page does not clearly say whether Costco gas spending counts toward the $7,000 cap, so I would not assume either way. Check Citi’s terms if you spend near the limit.
Eligibility also matters. “Eligible gas” and “eligible EV charging” depend on how the merchant is coded, so a station that looks like gas to you may not qualify. Check the card’s terms and watch your first statements for the category it assigns.
If you spend more than $7,000 on gas a year, the extra earns only 1%. At that point, compare the card with others for the overflow.
Also note a practical limit. Costco gas stations accept Visa, as the Mental Floss report says, but they are only useful if there is one near where you drive. A bonus rate you cannot use is not a bonus.
Travel, Restaurants and Spending Abroad
The 3% rate covers restaurants and eligible travel, including Costco Travel. That makes it useful beyond the warehouse, since dining out is a regular expense for many households.
Both sources report no foreign transaction fees. For a traveler, that removes a cost that many cards add to purchases made abroad. Visa is also widely accepted overseas, though that last point is general knowledge, not from my sources.
As with gas, “eligible travel” depends on merchant coding and the card’s terms. Check how the card defines it before you book a trip around the reward.
If you travel often, compare this card with a travel-focused card. A card with a different reward structure may suit your trips better, even if Costco gas keeps the co-branded card in your wallet for local use.
A Worked Example With Real Arithmetic
Numbers make the decision easier. This example is hypothetical, built from the rates above, so replace the spending figures with your own.
Imagine a household with these annual costs:
| Category | Annual spend | Rate | Reward |
|---|---|---|---|
| Gas at Costco | $2,400 | 5% | $120 |
| Other gas | $1,800 | 4% | $72 |
| Restaurants and travel | $4,000 | 3% | $120 |
| Costco and Costco.com | $6,000 | 2% | $120 |
| Everything else | $10,000 | 1% | $100 |
| Total | $24,200 | $532 |
Compare that with a hypothetical flat 2% cash-back card on the same $24,200. That would earn $484. The Costco card comes out about $48 ahead in this scenario.
Now change the picture. A household that buys no gas, spends $4,000 on restaurants and travel, $6,000 at Costco, and $10,000 elsewhere earns $120 + $120 + $100 = $340 on the Costco card. A flat 2% card on the same $20,000 earns $400, which is $60 more.
The lesson is simple. The co-branded card wins when gas and dining are a big share of your spending, and loses when most of your money goes into the 1% bucket.
Run the same table with your own year of statements. It takes ten minutes and tells you more than any ranking.
Who the Card Fits
Picking a Visa credit card for Costco should start with your habits, not the marketing. It tends to suit people who already shop at Costco regularly and fill the car there. The 5% rate on Costco gas is the standout, and the 4% on other eligible gas and EV charging helps if you drive a lot.
It also suits households that eat out and travel often, because of the 3% rate on restaurants and eligible travel.
It suits people who value simplicity: one card, one certificate a year, and a bonus on warehouse purchases.
It fits poorly for people who rarely visit a warehouse, who want rewards deposited to a bank account, or who spend most of their money outside the bonus categories. For them, a flat-rate Visa card may do better.
It also fits poorly for anyone who carries a balance. The next section explains why.
Interest Can Erase the Rewards
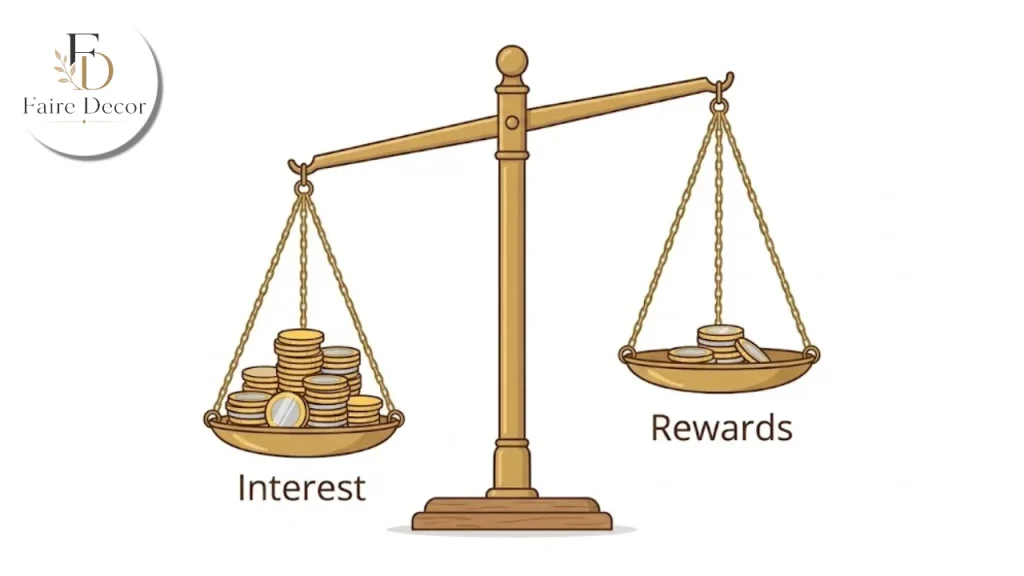
The regular APR runs 18.99% to 26.99% variable, according to both sources. That is high enough to wipe out any rewards you earn.
Take a simple case. A $1,000 balance carried for a full year at 18.99% costs roughly $190 in interest, ignoring compounding and payments. Earning 2% on that $1,000 is $20.
So a Visa credit card for Costco only pays if you clear the balance every month. If you cannot do that, a lower-rate card is the better tool, and rewards should not drive the choice.
Pay on time, every time. Set up automatic payments for at least the minimum and pay the full balance when you can. Late payments bring fees and can hurt your credit.
Online Orders at Costco.com
Online payment rules differ slightly from the warehouse. The Mental Floss report says Mastercard credit cards are accepted for online orders on Costco’s website, though not in warehouses.
That means you could use a non-Visa credit card online. But the Costco Anywhere Visa pays 2% on purchases from Costco and Costco.com, so using it online keeps you in the bonus tier.
Whether that beats another card depends on the other card’s rate. Compare the rates, not the logos, and check that online purchases are not excluded from any promotion you plan to use.
Using the Card for Home Projects
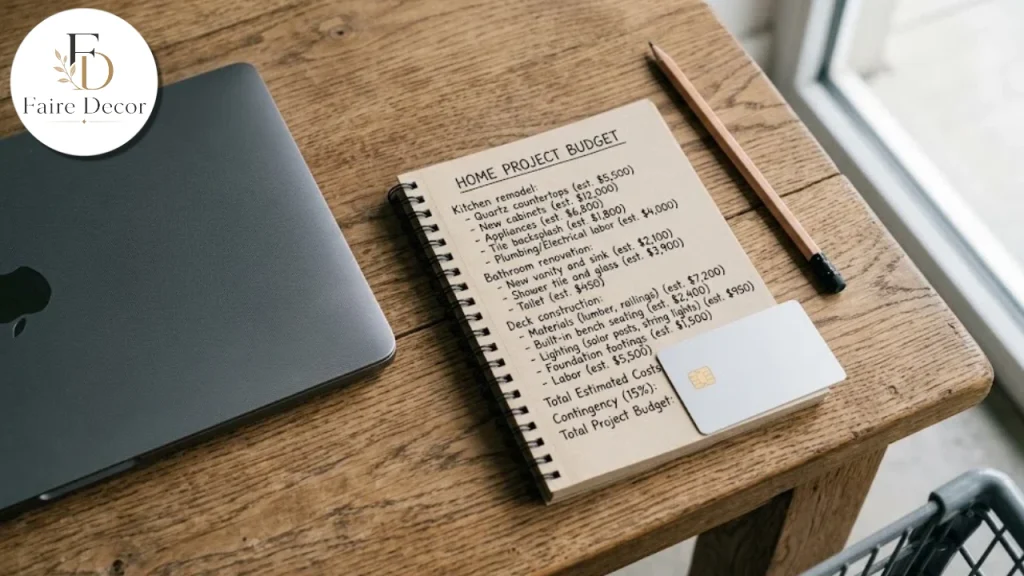
Costco sells more than groceries. Many shoppers buy furniture, appliances, and home goods there, so aVisaa credit card for Costco can sit at the center of a renovation budget. This is general knowledge, so check what your local warehouse stocks.
If you plan a big purchase, the 2% rate on Costco spending is the relevant one, and a $3,000 warehouse purchase would earn $60 in rewards on those terms. That is a small bonus on top of whatever price you negotiated, not a reason to buy something you do not need.
Before you commit, plan the project. Browse ideas for the best home furnishings so you know what you want, and compare options before you swipe.
Kitchen upgrades are a common big-ticket item. These notes on modern kitchen cabinets can help you set a budget, though you should check current prices yourself.
For a bigger job, such as a new room, read about home additions first. Large projects usually cost more than the first estimate, so do not finance one on a card you cannot pay off.
Smaller fixes work well with a warehouse run: an over-the-washer-and-dryer shelf or a handful of styling pieces from these home decor ideas. Spending on these smaller items is easier to pay off in a single billing cycle.
The rule of thumb is the same as before. Use the card to earn rewards on spending you had already planned, and pay it off in full.
Other Ways to Pay and Other Cards to Consider
Because Costco accepts any Visa credit card, you are free to compare. A flat-rate cash-back Visa from another bank may beat the co-branded card if your spending falls outside the bonus categories. That is general advice, not a sourced comparison.
A debit card is the other option. Costco takes almost any debit card, including Mastercard-branded debit, as the Mental Floss report notes. A debit card avoids interest, though it does not earn the same rewards and may offer different consumer protections than a credit card. Check your bank’s terms.
If you plan to compare cards, build a short list of two or three and run the same worked example for each. Look at the fee, the APR, the reward structure, and how rewards are redeemed.
Ask three questions of any card. What do I actually spend, and where? Will I pay it off every month? Can I use the reward in a way that suits me?
How to Apply and What to Expect
The card is aimed at Costco members, and both sources say a paid Costco membership is required for the no-annual-fee terms. Check the current membership fee and tier before you apply.
You will need a credit profile in the strong range. Experian lists the recommended score as “Exceptional” on the FICO Score 8 scale, and creditcards.com places it in the “Excellent” range. A lower score does not mean automatic denial, but your chances may drop.
Applying usually triggers a hard inquiry on your credit report. That is common credit practice, not a sourced figure, so ask the issuer about it before applying. Avoid applying for several cards at once.
Once approved, keep your Costco membership active. The terms tie the card to a paid membership, so if you let the membership lapse, check with the issuer what happens to your card.
A Five-Step Decision Checklist
Before you apply, work through these steps. They take under half an hour.
List your spending. Pull twelve months of statements and sort them into gas, restaurants and travel, Costco, and everything else.
Run the table. Apply the rates from the worked example to your own numbers and compare the result with a flat-rate card.
Check the membership. Confirm the current fee and decide whether you would hold the membership regardless.
Test your habits. Be honest about whether you pay in full each month. If not, rewards should not be your priority.
Read the terms. Open the issuer’s page and confirm rates, caps, the certificate rules,s and the APR.
If the answer is yes to all five, the Visa credit card for Costco may suit you well. If any step gives you pause, wait and compare.
Budgeting a Warehouse Trip
Bulk buying is where good intentions go to die. A cart full of discounted items can still cost more than a small trip to a regular store if half of it goes to waste.
Make a list before you go, check your pantry and freezer, and decide on a spending limit. Use the card for what is on the list, not for what looks tempting at the end of an aisle.
Rewards are a rounding error against impulse purchases. A 2% reward on a $200 detour is $4, and the detour itself is $200.
Keep receipts for large items and check the return policy at the time of purchase, because policies can change by product. That is general advice, so read the policy yourself.
Protecting Your Account and Your Credit
Turn on transaction alerts in the issuer’s app so you see every charge as it posts. Check your statements monthly, and report any charge you do not recognize right away.
Never share your card number or one-time codes with someone who contacts you. Banks do not ask for them. Costco members are a common target for scam messages that claim a prize or a problem with your membership, so go to the official site yourself instead of clicking a link. This is general security advice.
Check your credit reports on a regular schedule. In the United States, you can request your reports from the three credit bureaus through the official federal channel. Look for accounts you did not open.
If you lose the card, report it immediately and ask for a replacement. Update any autopay that depends on the old number.
Common Mistakes
Carrying a balance. Interest will outrun the rewards almost every time.
Assuming only the co-branded card works at Costco. Any Visa credit card does.
Forgetting to redeem the annual certificate. Set a reminder when it arrives.
Overspending to chase a bonus. A 2% reward on something you did not need is still a 98% loss.
Ignoring the gas cap. The 4% rate applies only to the first $7,000 of combined eligible spending each year, then drops to 1%.
Using it for categories that earn 1%. Another card may pay more outside the bonus categories.
Skipping the terms. Rates, caps,s and benefits change, so read the current cardmember agreement.
Quick Answers
Does Costco only accept Visa? For credit cards in U.S. warehouses, yes. Debit cards of many networks, cash, checks,ks and EBT are also accepted.
Do I need the Costco card to use Visa at Costco? No. Any Visa credit card works.
What does the Costco Anywhere Visa pay? Per two sources, 5% on Costco gas, 4% on other eligible gas and EV charging up to $7,000 a year, 3% on restaurants and eligible travel, 2% at Costco, and 1% elsewhere.
How are rewards paid? As an annual reward certificate redeemable at U.S. Costco warehouses for cash or merchandise.
Isa Visa credit card for Costco worth it? It depends on your spending. Run the numbers, pay in full each month, and confirm current terms on the issuer’s site before you apply.
FAQs:
Does Costco only accept Visa credit cards?
In U.S. warehouses, yes: Visa is the only credit card accepted. Costco also takes most debit cards (including Mastercard-branded debit), cash, checks, and EBT. Mastercard credit cards work for online orders, per Mental Floss.
Do I need the Costco Anywhere Visa card to pay at Costco?
No. Any Visa credit card from any bank works at the register. The co-branded card only matters if its rewards beat the card you already hold.
What rewards does the Costco Anywhere Visa Card by Citi earn?
Per creditcards.com (updated March 9, 2026) and Experian: 5% on gas at Costco, 4% on other eligible gas and EV charging up to $7,000 a year (then 1%), 3% on restaurants and eligible travel, 2% on Costco and Costco.com purchases, and 1% on everything else.
How do I get my Costco card rewards?
As an annual reward certificate, redeemable for cash or merchandise at U.S. Costco warehouses, including Puerto Rico.
Is there an annual fee?
Both sources list $0, but a paid Costco membership is required. Check the current membership fee and tier.
Is the Costco card worth it if I carry a balance?
Usually not. The APR is 18.99% to 26.99% variable, so interest on a $1,000 balance (about $190 a year at 18.99%) far outweighs 2% rewards.